For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Can the Next Generation Afford Home Ownership?

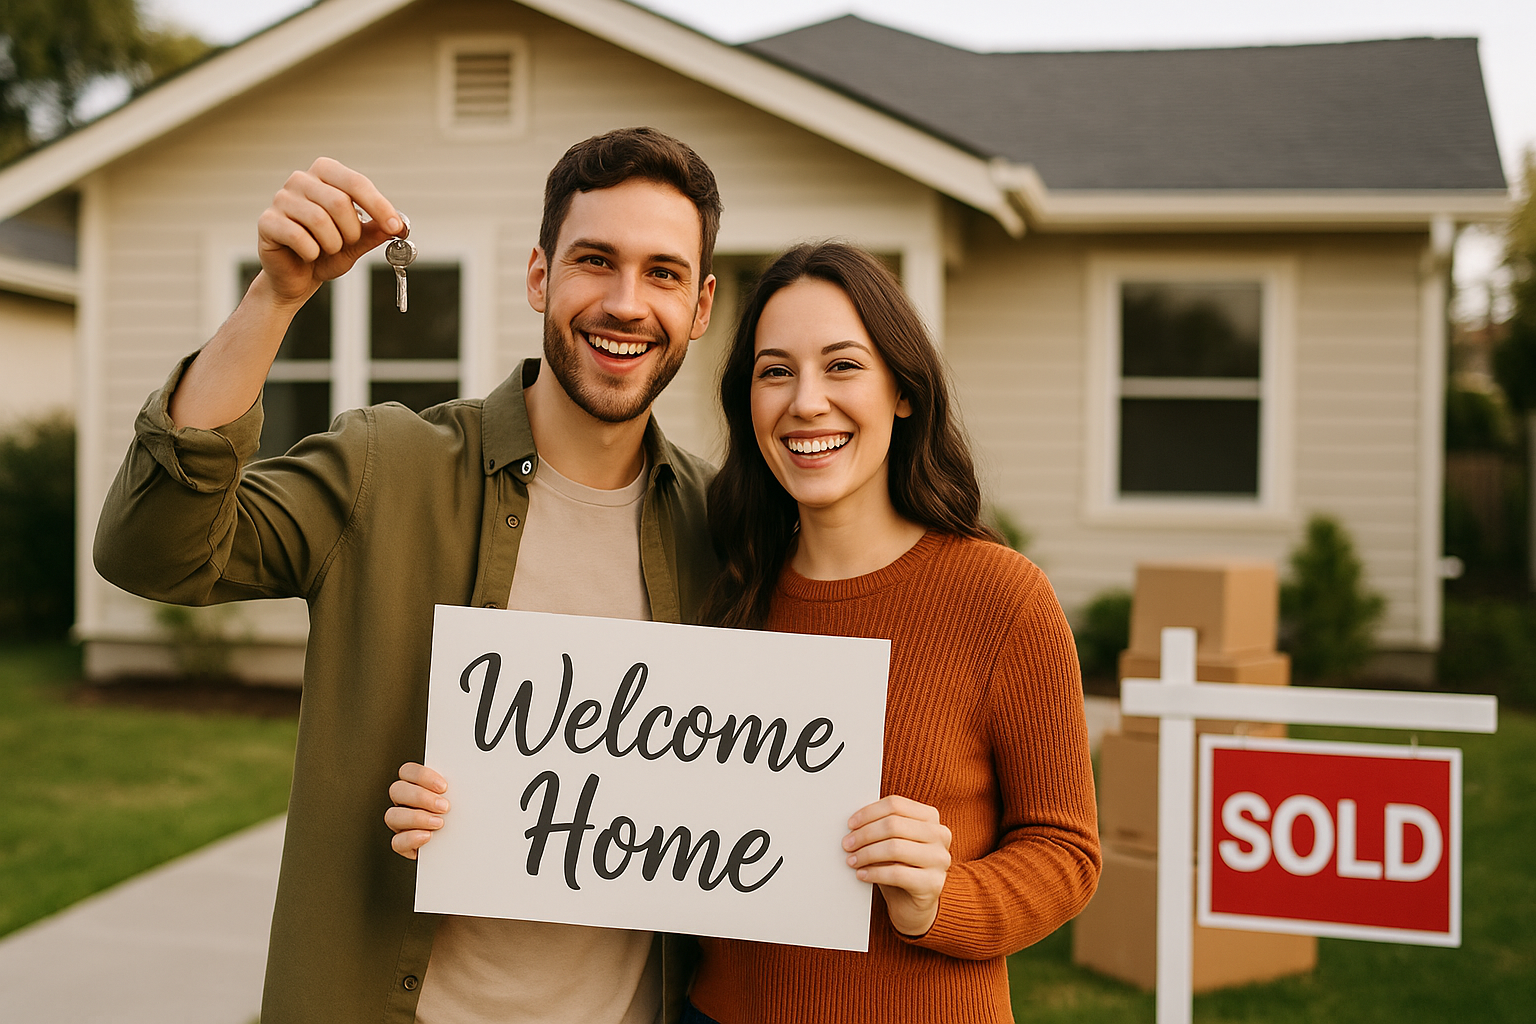
A happy, young couple just got the keys to their first home.

This article explores factors influencing housing affordability, the impact of current economic conditions, and future prospects. Readers will discover insights into decision-making for first-time real estate purchases and strategic approaches to homeownership.

July 22, 2025
A happy, young couple just got the keys to their first home.
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

It used to be a rite of passage to buy a starter home by your late 20s. Today, many young adults wonder whether that milestone is slipping out of reach. Rising prices, higher borrowing costs, and a limited supply of entry‑level properties have created the most challenging landscape for first‑time buyers in decades. But with the right strategy, the dream of owning a home can still move from uncertainty to peace of mind.

The Roadblocks Facing Young Buyers

Sticker shock is only part of the story. After a pandemic‑era boom, median home prices are roughly 40 % higher than five years ago, while wages have grown less than half that pace. At the same time, 30‑year mortgage rates that once hovered near 3% have doubled, slashing the amount a buyer can finance on the same monthly payment.

Student debt and lifestyle inflation complicate saving. A 20% down payment on a $450,000 starter home is $90,000—tough to accumulate while carrying student loans and paying record‑high rents. It’s no surprise that nearly 60% of millennials who hope to buy in the next five years expect to receive family help.

Supply is historically tight. Baby boomers are aging in place, and institutional buyers continue to purchase single‑family rentals. With fewer existing homes hitting the market and new‑construction costs elevated, competition pushes prices even higher.

These hurdles are real, but they’re not immovable. Big goals are achieved by breaking them into a series of smaller, controllable steps.

Creative Paths to the Front Door

  • Think beyond the classic 20 % down. Federal Housing Administration (FHA) loans require as little as 3.5 % down, while many state housing agencies offer zero‑interest silent seconds to first‑time buyers. Just remember that a lower down payment means a higher monthly obligation, so run the numbers with a fiduciary.
  • House hacking turns a liability into an asset. Buying a duplex and renting the other unit—or even taking on a roommate—can offset the mortgage and help you qualify for a larger loan.
  • Shared‑equity arrangements trade future appreciation for help today. Several fintech firms will contribute part of your down payment in exchange for a slice of the home’s price appreciation at sale. This option can bridge the gap for savers who are close, but not quite there.
  • Tap retirement savings cautiously. First‑time buyers can withdraw up to $10,000 of IRA funds penalty‑free, and some employer plans allow loans against 401(k)s. These moves carry opportunity cost, so coordinate them within a broader financial‑planning framework and consult your financial advisor first.

With each of these strategies, the buyer must weigh taxes, cash‑flow risk, and long‑term goals.

Action Plan: Turning Dreams into Deeds

  • Know your credit profile. Aim for a FICO score of 740+ to unlock the best rates, but don’t be discouraged if you’re lower—an advisor can map out incremental improvements.
  • Set a realistic price range. Housing payments (principal, interest, taxes, insurance, HOA) should generally stay below 30 % of gross income after factoring in other debts.
  • Automate a future mortgage savings plan. Treat an online, high‑yield savings account like a monthly bill; even $300 a month grows to nearly $19,000 in five years at 4% interest.
  • Stress‑test the budget. Model scenarios for rate increases, job changes, or unexpected repairs so you enter the market with eyes wide open.
  • Leverage professional guidance early. A financial advisor can coordinate lender pre‑approval, down‑payment assistance, and tax strategies while ensuring homeownership fits within your broader retirement and investment plan.
  • Set aside an emergency fund. This will help to care for unexpected expenses quickly.

Key Takeaways

Homeownership is tougher for first-time buyers today, but it’s not impossible. Success hinges on diligent planning. Consider all financing options, including FHA loans and shared equity; one just might be right for you. Be sure to protect long-term wealth by fitting a purchase into an overall financial journey. Partnering with a financial professional can help translate today’s dream into tomorrow’s equity.
Other content you may like

  • Living With the Dog Days of Summer

    Living With the Dog Days of Summer

    July 28, 2023
    There are several things that can be done to beat the heat this summer. With a little diligence and preparation, we should be able to enjoy these dog days of summer safely.
    Read this Article
  • hope with peaceful color background and dandelion blowing in the wind

    Hope and Life after COVID-19

    April 4, 2020
    Hope and Life After COVID-19 There is little doubt that a time will come when we say the worst of is behind us, but life after COVID-19 will likely look much different. Few events are as truly worldwide as this or have had such a rapid impact on shaping our daily lives and routines.  Our […]
    Read this Article
  • What's Driving the Market

    Podcast Highlight - Answering Client Questions: What’s up with the Recession?

    March 13, 2023
    There’s been a moving definition over the last year and a half about what a Recession is and whether we’re in one. The team talks about what most analysts they respect are saying and some suggestions on how you can prepare for heading into a recession in 2023, in ways similar to how the East coast prepares for a hurricane.
    Read this Article
  • The 8th Best August Stock Performance since 1926

    September 7, 2020
    This special report looks at the historical market returns in the context of presidential elections, which parties are in control of Congress, and various government election outcomes. While nobody can predict the future, and past results don't guarantee future outcomes, this report gives some insights as to what the financial landscape might look like after the 2020 elections.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset