Call Our Office
CA | (559) 384-2900
TN | (931) 299-7002
Your Money
Your Life
Your Way
You are now leaving the Strong Valley Wealth & Pension, LLC ("Strong Valley") website. By clicking on the "Schwab Alliance Access" link below you will be entering the Charles Schwab & Co., Inc. (“Schwab”) Website. Schwab is a registered broker-dealer, and is not affiliated with Strong Valley or any advisor(s) whose name(s) appears on this Website. Strong Valley is/are independently owned and operated. Schwab neither endorses nor recommends Strong Valley. Regardless of any referral or recommendation, Schwab does not endorse or recommend the investment strategy of any advisor. Schwab has agreements with Strong Valley under which Schwab provides Strong Valley with services related to your account. Schwab does not review the Strong Valley website(s), and makes no representation regarding the content of the Website(s). The information contained in the Strong Valley website should not be considered to be either a recommendation by Schwab or a solicitation of any offer to purchase or sell any securities.
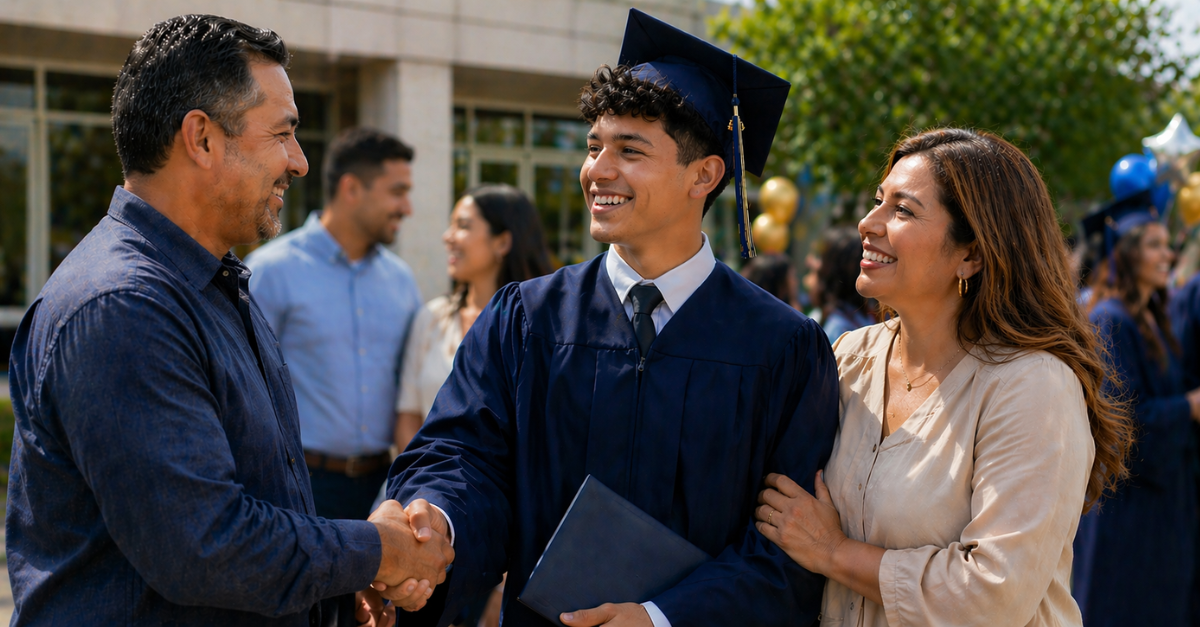
What’s the best way to help your high school senior step into adulthood? This article delves into important financial skills that will help these young adults prepare for successful next steps, whether that means additional education, the military or joining the workforce.

Graduation season is exciting, but it also marks the beginning of new financial decisions. Whether a high school senior is heading to college, trade school, military service, or directly into the workforce, this is an ideal time for families to begin reinforcing healthy money habits.
These five practical planning tips can help high school seniors build confidence, avoid common mistakes, and enter adulthood on stronger financial footing.
The planning process can begin with the next 12 months. A student may need money for tuition, housing, transportation, books, work clothes, or a first car. From there, families can look beyond the first year to goals such as finishing school with manageable debt, building savings, or starting retirement contributions early. Clear and specific goals can make everyday spending decisions much easier.
A basic budget does not need to be complicated. A student can list expected income from part-time work, family support, scholarships, or gifts, then compare it with regular expenses. Parents can encourage students to separate essentials from discretionary spending and review transactions each month. Using a budgeting app or spreadsheet can help them stay organized and spot habits before they become problems.
Before signing for any loans or opening credit card accounts, students should understand how borrowing works. They should know the difference between federal and private student loans, how a balance and interest affect total repayment, and why making on-time payments matter. Used carefully, credit can help build a financial history. Used carelessly, it can create stress that lasts for years.
Unexpected expenses can arise quickly, especially during the transition to adulthood. A realistic first goal for an emergency fund may be saving $500 to $1,000 for car repairs, medical co-pays, unexpected travel, or other surprise costs. Once income becomes more consistent, that emergency reserve can continue to grow. Even a modest cushion can reduce the need to rely on high-interest debt.
Education, training, and skill development can have a lasting impact on earning potential. Parents can encourage students to explore scholarships, internships, apprenticeships, and opportunities to build real-world experience. Once earned income begins to come in, learning the basics of saving and investing, including the power of long-term compounding, can become a valuable advantage.
The transition out of high school is about more than choosing a next step. It is also a chance for students and families to build decision-making habits that can support long-term financial well-being. Starting with clear goals is the first step to establishing a workable budget. Next, it’s important to understand the impact of debt and borrowing on the budget. Parents can also emphasize the importance of starting an emergency fund to help preserve the budget when something unexpected happens. These steps will not only help the young graduate begin adult life on a stronger financial footing, but it will also help set the stage for the student to more freely invest in their own future.
Families navigating education funding, budgeting decisions, or broader wealth planning questions may benefit from guidance from a trusted financial professional who can help evaluate strategies that fit their unique goals and circumstances.