Call Our Office
CA | (559) 384-2900
TN | (931) 299-7002
Your Money
Your Life
Your Way
You are now leaving the Strong Valley Wealth & Pension, LLC ("Strong Valley") website. By clicking on the "Schwab Alliance Access" link below you will be entering the Charles Schwab & Co., Inc. (“Schwab”) Website. Schwab is a registered broker-dealer, and is not affiliated with Strong Valley or any advisor(s) whose name(s) appears on this Website. Strong Valley is/are independently owned and operated. Schwab neither endorses nor recommends Strong Valley. Regardless of any referral or recommendation, Schwab does not endorse or recommend the investment strategy of any advisor. Schwab has agreements with Strong Valley under which Schwab provides Strong Valley with services related to your account. Schwab does not review the Strong Valley website(s), and makes no representation regarding the content of the Website(s). The information contained in the Strong Valley website should not be considered to be either a recommendation by Schwab or a solicitation of any offer to purchase or sell any securities.
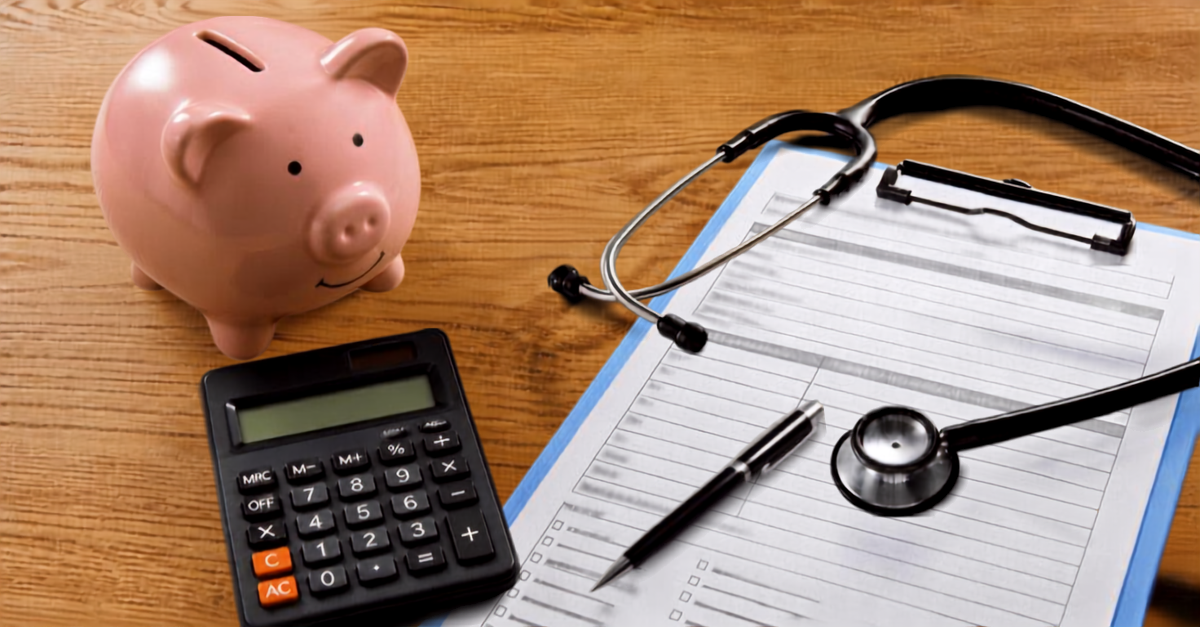
Could an HSA play a larger role in your financial plan? Health savings accounts may help eligible individuals and families prepare for qualified medical expenses today and in the future. Learn how contributions, health care reserves, and broader goals can work together.

Health savings accounts, or HSAs, can be a useful planning tool for eligible individuals and families enrolled in high-deductible health plans. When health care costs rise, an HSA may help create a dedicated reserve for qualified medical expenses while offering potential tax advantages.
The opportunity is not only about paying today's medical bills. For some households, an HSA can also become part of a broader conversation about cash flow, emergency reserves, and long-term health care expenses.
An HSA generally allows eligible individuals to make tax-favored contributions, build the account over time, and use the funds tax-free for qualified medical expenses. That combination can make the account useful for both current health care spending and future planning.
Still, an HSA is connected to a high-deductible health plan, which may involve meaningful upfront costs. The value of the account depends on eligibility, cash flow, expected medical needs, and how the household uses the plan.
For 2026, the HSA contribution limit is $4,400 for self-only coverage and $8,750 for family coverage. Individuals age 55 and older may be eligible for an additional $1,000 catch-up contribution.
The IRS also adjusts high-deductible health plan requirements. For 2026, minimum deductibles and out-of-pocket maximums moved higher, which makes it important to understand how the health plan and the HSA work together before choosing coverage.
Many people think of an HSA only as a reimbursement account. Used that way, it can still help pay current medical expenses. But some account holders may also use the HSA to build a reserve for future qualified medical costs.
It can also be helpful to coordinate HSA contributions with payroll deductions, employer contributions, and anticipated medical expenses. A steady contribution approach may make the account easier to use throughout the year, although the right approach depends on individual circumstances.
An HSA is most useful when it is viewed alongside the rest of the financial picture. A household may want to consider current medical needs, available cash reserves, insurance coverage, and long-term goals before deciding how much to contribute or whether to invest any portion of the account.
For some people, the account may be used primarily for near-term expenses. For others, it may become a longer-term reserve for future health care costs. Either approach can be reasonable when it reflects the person's needs, risk tolerance, and overall plan.
Business owners may also benefit from clear HSA education during benefits conversations. Employees often make better decisions when they understand the deductible, the potential out-of-pocket costs, and the role an HSA may play in preparing for those expenses.
Clear communication can help employees see the HSA as more than an add-on to a health plan. It can be part of a broader conversation about health care costs, household budgeting, and financial confidence.
Health care costs can affect both current cash flow and long-term planning. Strong Valley Wealth & Pension can help you think through how HSA contributions, health care reserves, and broader financial goals may fit together within your overall financial strategy.