For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Can the Next Generation Afford Home Ownership?

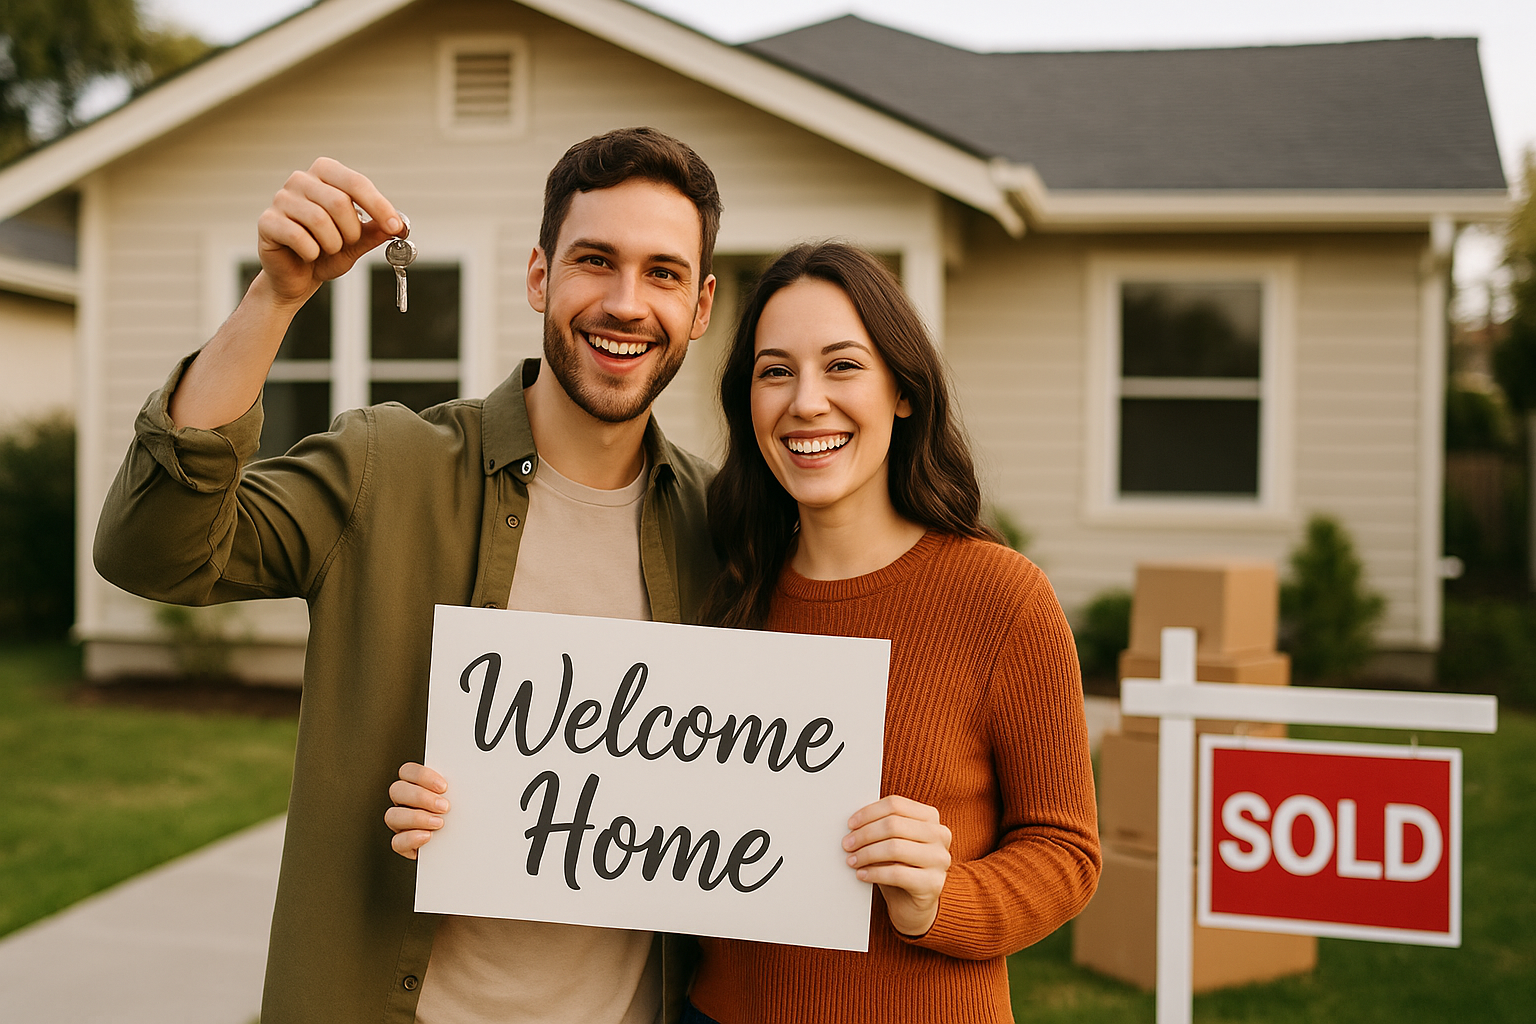
A happy, young couple just got the keys to their first home.

This article explores factors influencing housing affordability, the impact of current economic conditions, and future prospects. Readers will discover insights into decision-making for first-time real estate purchases and strategic approaches to homeownership.

July 22, 2025
A happy, young couple just got the keys to their first home.
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

It used to be a rite of passage to buy a starter home by your late 20s. Today, many young adults wonder whether that milestone is slipping out of reach. Rising prices, higher borrowing costs, and a limited supply of entry‑level properties have created the most challenging landscape for first‑time buyers in decades. But with the right strategy, the dream of owning a home can still move from uncertainty to peace of mind.

The Roadblocks Facing Young Buyers

Sticker shock is only part of the story. After a pandemic‑era boom, median home prices are roughly 40 % higher than five years ago, while wages have grown less than half that pace. At the same time, 30‑year mortgage rates that once hovered near 3% have doubled, slashing the amount a buyer can finance on the same monthly payment.

Student debt and lifestyle inflation complicate saving. A 20% down payment on a $450,000 starter home is $90,000—tough to accumulate while carrying student loans and paying record‑high rents. It’s no surprise that nearly 60% of millennials who hope to buy in the next five years expect to receive family help.

Supply is historically tight. Baby boomers are aging in place, and institutional buyers continue to purchase single‑family rentals. With fewer existing homes hitting the market and new‑construction costs elevated, competition pushes prices even higher.

These hurdles are real, but they’re not immovable. Big goals are achieved by breaking them into a series of smaller, controllable steps.

Creative Paths to the Front Door

  • Think beyond the classic 20 % down. Federal Housing Administration (FHA) loans require as little as 3.5 % down, while many state housing agencies offer zero‑interest silent seconds to first‑time buyers. Just remember that a lower down payment means a higher monthly obligation, so run the numbers with a fiduciary.
  • House hacking turns a liability into an asset. Buying a duplex and renting the other unit—or even taking on a roommate—can offset the mortgage and help you qualify for a larger loan.
  • Shared‑equity arrangements trade future appreciation for help today. Several fintech firms will contribute part of your down payment in exchange for a slice of the home’s price appreciation at sale. This option can bridge the gap for savers who are close, but not quite there.
  • Tap retirement savings cautiously. First‑time buyers can withdraw up to $10,000 of IRA funds penalty‑free, and some employer plans allow loans against 401(k)s. These moves carry opportunity cost, so coordinate them within a broader financial‑planning framework and consult your financial advisor first.

With each of these strategies, the buyer must weigh taxes, cash‑flow risk, and long‑term goals.

Action Plan: Turning Dreams into Deeds

  • Know your credit profile. Aim for a FICO score of 740+ to unlock the best rates, but don’t be discouraged if you’re lower—an advisor can map out incremental improvements.
  • Set a realistic price range. Housing payments (principal, interest, taxes, insurance, HOA) should generally stay below 30 % of gross income after factoring in other debts.
  • Automate a future mortgage savings plan. Treat an online, high‑yield savings account like a monthly bill; even $300 a month grows to nearly $19,000 in five years at 4% interest.
  • Stress‑test the budget. Model scenarios for rate increases, job changes, or unexpected repairs so you enter the market with eyes wide open.
  • Leverage professional guidance early. A financial advisor can coordinate lender pre‑approval, down‑payment assistance, and tax strategies while ensuring homeownership fits within your broader retirement and investment plan.
  • Set aside an emergency fund. This will help to care for unexpected expenses quickly.

Key Takeaways

Homeownership is tougher for first-time buyers today, but it’s not impossible. Success hinges on diligent planning. Consider all financing options, including FHA loans and shared equity; one just might be right for you. Be sure to protect long-term wealth by fitting a purchase into an overall financial journey. Partnering with a financial professional can help translate today’s dream into tomorrow’s equity.
Other content you may like

  • Q1 2022: Greatest Hits

    Q1 2022: Greatest Hits

    March 15, 2022
    Looking for stats on market volatility in uncertain times? These stock market numbers going back to 1950 might help you stay the course. In addition, here’s an overview of 2022’s 1st quarter in all the issues that matter: stock and bond returns, money market assets, growth vs value, interest rates, and the effects of inflation. Included is an important visual showing how a diversified portfolio can work even when it may not feel so good.
    Read this Article
  • April Student of the Market

    Stock Market History for Your Future

    April 27, 2022
    Do you feel your satisfaction level with the market is tracking with the norm? Maybe this brief history of long term stock performance might help change your mind. This month’s Student of the Market shows the numbers on how $1,000 invested in 1926 grew to over $14 million and how best days for stocks tend to closely follow the worst days.
    Read this Article
  • Build Your Financial Foundation

    December 29, 2023
    Successful money management requires regular reviews. Each year, you should pull all your records together and take a close look at your entire financial picture. Here are six steps that can help you put your financial affairs in order so that your financial foundation will be strong.
    Read this Article
  • male financial expert on video thumbnail

    Video: Solve It – Preparing for Change

    January 5, 2020
    The old model of simple diversification using US Stocks and Bonds may need to be expanded into a more diversified approach. Strong Valley takes each client situation into account and implements more complex strategies and models where applicable.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset