For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Required Minimum Distributions & Tax Strategies

Are you familiar with the IRS’s required minimum distributions (“RMDs”)? Learn about RMDs and strategies to effectively reduce taxes, optimize financial planning and maximize your legacy by preserving wealth in retirement for what is most important to you.

March 17, 2025
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

Once retirees reach age 73 (as per the latest SECURE Act changes), they must start taking Required Minimum Distributions (RMDs) from tax-deferred accounts such as 401(k)s and traditional IRAs. Failure to comply can result in hefty penalties. Understanding how to calculate and manage RMDs is essential to maintaining tax efficiency and financial stability.

How to Calculate and Take RMDs Without Unnecessary Tax Burdens

The IRS provides a formula for RMD calculations based on life expectancy and account balances. Here’s how to approach it:

  • Use the IRS Uniform Lifetime Table: Find the appropriate distribution factor based on age and apply it to the account balance at year-end.
  • Plan for Taxes: RMDs are treated as ordinary income and may push retirees into a higher tax bracket.
  • Consider Withdrawal Timing: Spreading RMDs throughout the year rather than taking a lump sum can help manage tax liabilities.


Roth Conversions and Other Tax-Efficient Withdrawal Strategies

Retirees can mitigate the tax impact of RMDs by incorporating these strategies:

  • Roth Conversions: Strategically transferring funds from a traditional IRA to a Roth IRA can reduce future RMD obligations, as Roth IRAs are not subject to RMDs.
  • Tax Bracket Management: Withdraw funds strategically to avoid bumping into a higher tax bracket.
  • Delaying Social Security: If possible, delaying Social Security benefits allows retirees to withdraw from tax-deferred accounts earlier, reducing future RMD burdens.

Charitable Giving Strategies, Such as Qualified Charitable Distributions (QCDs)

For charitably inclined retirees, QCDs offer a tax-efficient way to satisfy RMD requirements:

  • What is a QCD? Retirees can donate up to a certain amount each year directly from their IRA to a qualified charity.
  • Tax Benefits: QCDs satisfy RMD obligations without increasing taxable income.
  • Estate Planning Considerations: Charitable donations can reduce estate taxes and leave a philanthropic legacy.

By proactively planning with a financial professional to leverage tax-efficient strategies, and explore charitable giving, retirees can minimize tax burdens and maximize their retirement wealth.
Other content you may like

  • How to Measure Your Portfolio in Uncertain Times

    How to Measure Your Portfolio in Uncertain Times

    May 10, 2022
    Too often during uncertain times, we inadvertently compare ourselves to the people around us – and that leads us to make financial mistakes. Consider looking at the big picture instead to make sure your investment helps you towards your true life goals. This article helps with examples that clarify changing to a bigger perspective.
    Read this Article
  • Investing in Your Vacation

    Investing in Your Vacation

    July 1, 2023
    Taking a vacation is an investment in your own well-being, in your career, and in the company you work for. Are vacations a priority to you or do you avoid this important investment? This article takes a look at some of the reasons for skipping vacations, as well as the benefit you might not have considered.
    Read this Article
  • Podcast Highlight - Value vs Growth

    November 28, 2023
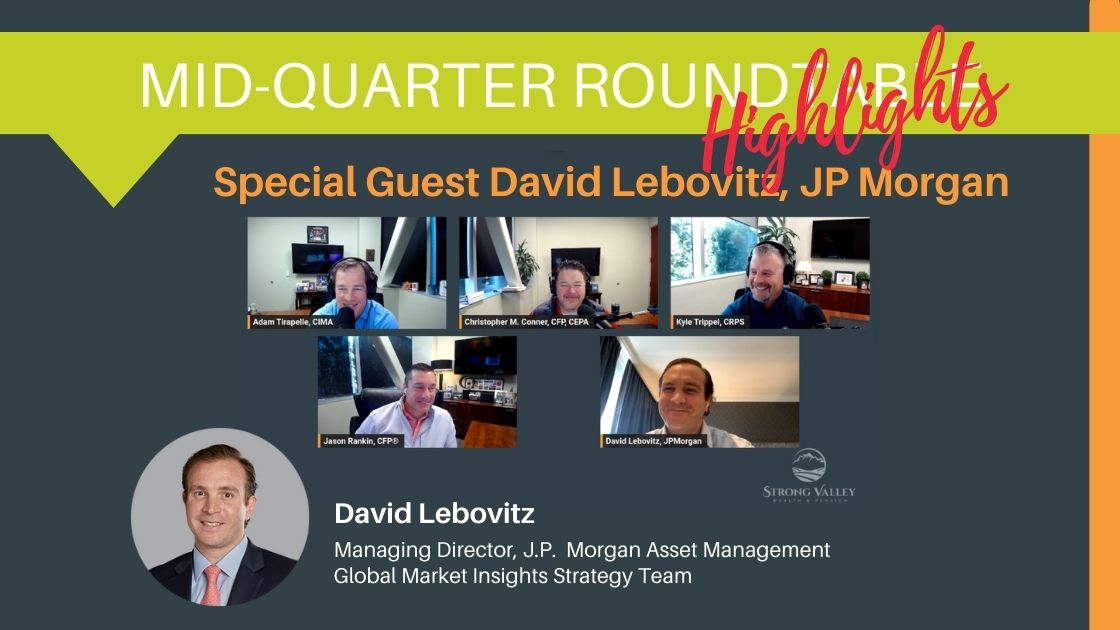
    David gives insight into the difference between being a value investor and investing in value as a style.
    Read this Article
  • A young family in a pumpkin patch

    October is the Time to Start Tax Planning

    October 20, 2025
    Learn the importance of starting tax planning in October, while there’s still time to make financial changes before January. Several strategies mentioned can have an impact on taxes, come April. Dive in to learn more about optimizing your taxes with early preparation.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset