For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Shelter From the Storm: What is Umbrella Coverage and How Much is Enough?

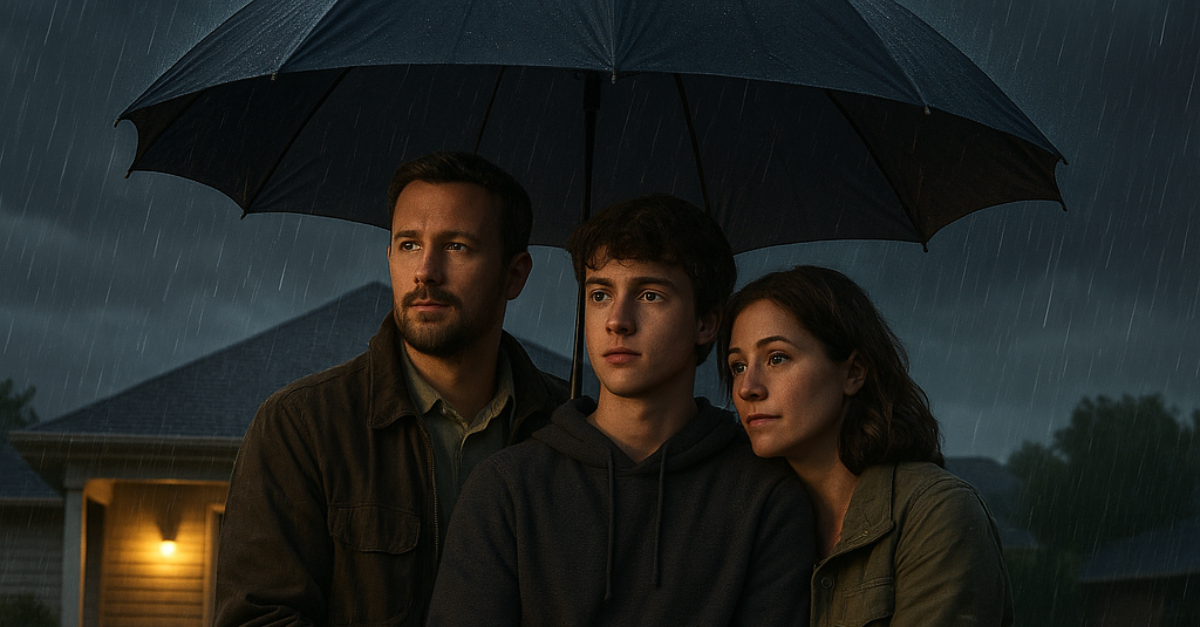
Life can bring surprise storms when you least expect them. Is homeowner’s and auto insurance enough to weather a bad storm, or is there something more? This article covers the purpose of umbrella coverage and how it can protect a household in a financial downpour.

June 3, 2025
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

Life can present some serious storms, and when it comes to financial liability, standard homeowner's insurance might feel as inadequate as a raincoat during a hurricane. That’s where umbrella insurance policies offer an additional layer of protection, when life’s little showers turn into a financial downpour. Umbrella policies are designed to help safeguard a property owner’s income, assets, lifestyle, and legacy, if someone is injured on the property or by a member of the household.

Understanding this protection requires a closer examination of the potential storm clouds and the valuable assets that may be at risk.

Determine the Right Amount of Coverage

Take an inventory of potential risks around the property.

  • Teenage Drivers: Less experience behind the wheel increases the risk of accidents.
  • Backyard Hazards: Pools, trampolines, and even playful pets can lead to unforeseen injuries on the property.
  • Everyday Accidents: A simple slip on an icy walkway can result in significant injury and liability.
  • Social Gatherings: Hosting parties, especially with alcohol, may increase an owner’s responsibility for guest’s well-being.

How much coverage is really needed?

A widely accepted guideline is to correlate potential umbrella insurance coverage to the obvious assets, including:

  • Home Equity: The value of the home minus the mortgage.
  • Savings and Investments: Checking and savings accounts, money market funds, stocks, bonds, and mutual funds.
  • Vehicles and Other Property: Cars, boats, RVs, and valuable personal items.
  • Future Earnings: This is especially crucial for high-income earners.

Coverage Guidelines Based on Financial Profile

Consider net worth and potential risks when determining coverage.

  • $1 Million: A good baseline for many homeowners with moderate assets.
  • $2 Million to $3 Million: This may be prudent for those with growing net worth, teenage drivers, pools or trampolines, or for those who frequently entertain.
  • $5 Million or More: May be recommended for high-net-worth individuals, professionals with significant earning potential, or those with multiple properties.

A Proactive Approach

Keep in mind that umbrella policies typically require certain minimum limits on underlying home and auto insurance. Be sure to review those policies, as they can provide a significant foundation for an umbrella policy.

Be proactive, don't wait for the storm clouds to gather. A well-chosen umbrella policy may help weather an unexpected financial downpour. Let’s discuss your circumstances and tailor a solution that provides the clarity you deserve.
Other content you may like

  • Christmas Shopping Lessons for Investors

    December 7, 2021
    There’s a generational cycle that is both fascinating and important to understand as an investor. Find out why it’s important to ask yourself, “Is that investment an innovation or an improvement on an existing product?” It could explain why today’s business environment seems flush with billionaires younger than 30. It’s also helpful when you’re deciding to invest in the right new product – Facebook and not MySpace for instance.
    Read this Article
  • Podcast Highlight - Fed Forecasts & Policy

    November 21, 2023
    Discussion centers around how inflation is tightly correlated with economic growth and the outlook, along with how outlook models have been working.
    Read this Article
  • Strong Valley Special Webinar - Sep 23 2020

    Immediate and Long-term Economic Outlook with special guest Strider Elass

    September 26, 2020
    The Strong Valley Advisor Team along with special guest Strider Elass will be giving broad insights on the economy. We discuss how the COVID recovery, exorbitant national debt, and the current political climate, may impact the economy in the immediate and distant future. Strider is a Senior Economist and is part of the First Trust Economics Team that Bloomberg has ranked as one of the top forecasters of the U.S. economy over the past several years.
    Read this Article
  • Podcast Highlight - Client Questions: T-Bills are simple, can they save the day?

    August 31, 2023
    The Team discusses how people are enjoying the interest rates that their conservative investments are paying but warns that cash vehicles are not long-term solutions.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset