Call Our Office
CA | (559) 384-2900
TN | (931) 299-7002
Your Money
Your Life
Your Way
You are now leaving the Strong Valley Wealth & Pension, LLC ("Strong Valley") website. By clicking on the "Schwab Alliance Access" link below you will be entering the Charles Schwab & Co., Inc. (“Schwab”) Website. Schwab is a registered broker-dealer, and is not affiliated with Strong Valley or any advisor(s) whose name(s) appears on this Website. Strong Valley is/are independently owned and operated. Schwab neither endorses nor recommends Strong Valley. Regardless of any referral or recommendation, Schwab does not endorse or recommend the investment strategy of any advisor. Schwab has agreements with Strong Valley under which Schwab provides Strong Valley with services related to your account. Schwab does not review the Strong Valley website(s), and makes no representation regarding the content of the Website(s). The information contained in the Strong Valley website should not be considered to be either a recommendation by Schwab or a solicitation of any offer to purchase or sell any securities.
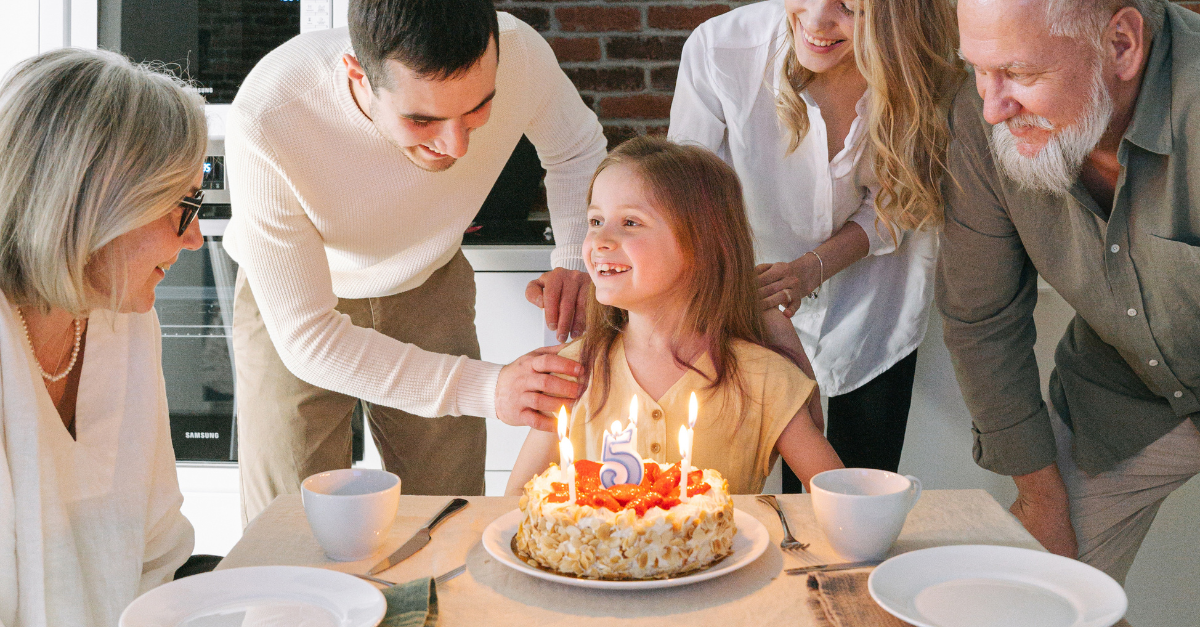
Are you part of the “sandwich generation?” Are you squeezed with competing pressures of caring for aging parents, raising kids, and trying to save for retirement, all at the same time? There are strategies that can help to balance these responsibilities. Take a look!

Many investors in their late 30s, 40s, and early 50s find themselves squeezed between competing responsibilities: saving for retirement, supporting children, and helping aging parents. This “sandwich generation” faces a unique set of financial and emotional challenges. Without a plan, the pressure can lead to reactive decisions that undermine long‑term security. With a structured approach and guidance, however, it is possible to strike a more sustainable balance.
The heart of the challenge is that all three goals—college, eldercare, and retirement—can be expensive, unpredictable, and emotionally charged. Parents naturally want to help children avoid excessive student debt, while the desire to care for aging parents can prompt generous financial or time commitments. At the same time, the clock is always ticking on retirement, and years of lost saving are difficult to replace. The risk is that retirement contributions get squeezed out as more urgent needs grab attention, leaving the future seeming stressful and underfunded.
The first step is to clarify priorities. A common principle is that retirement remains a foundational goal. Unlike education, which can be financed through loans, grants, or work‑study, and unlike some aspects of eldercare that may be supported through insurance, government programs, or shared family arrangements, there is no loan for retirement. If retirement savings fall short, the burden often shifts back onto adult children, continuing the cycle. Framing retirement as a non‑negotiable pillar can help future-retirees see that protecting their own future is not selfish; it is a form of long‑term family care.
The second step is to map out the timelines and magnitude of each obligation. Education costs can often be estimated with reasonable accuracy once children are in high school, factoring in school options, financial aid possibilities, and savings vehicles like 529 plans. Eldercare is more uncertain but can still be approached systematically by reviewing parents’ assets, income sources, insurance coverage, the housing situation, and likely care preferences. Retirement, meanwhile, can be modeled using age‑based savings benchmarks, projected Social Security benefits under different claiming strategies, and desired lifestyle and needs assumptions.
Once timelines and rough costs are on the table, a financial advisor’s role is to coordinate trade‑offs. For example, a family might decide to fully fund the retirement plan to obtain employer matches and maintain a target savings rate before allocating additional dollars towards college savings. They might commit to a certain level of support for parents, such as supplementing care costs or providing temporary housing, while also exploring long‑term care insurance, community resources, or government programs to reduce strain. The plan should be realistic about what the family can afford, rather than relying solely on best‑case scenarios.
Budgeting and cash‑flow management become especially important for the sandwich generation. Advisors can help clients identify areas where expenses can be trimmed or restructured—such as refinancing high‑interest debt, adjusting discretionary spending, or right‑sizing housing—to free up funds for savings and caregiving. Automated contributions to retirement and education accounts are valuable because they turn good intentions into consistent action, minimizing the impact of short‑term distractions or market news.
Communication is another vital element of a successful plan. Discussions with children about college choices and financing should be honest, emphasizing the trade‑offs between school selection, borrowing, and family resources. Similarly, conversations with parents about their finances, legal documents, and care preferences can be difficult but are essential for effective planning. Advisors can be neutral facilitators in these conversations, helping families discuss sensitive topics with less friction and more clarity.
Risk management also plays a major role. The sandwich generation should pay close attention to insurance coverage, including life, disability, health, and, where appropriate, long‑term care insurance. Adequate coverage can protect both current income and future savings, reducing the likelihood that an unexpected event derails multiple goals at once. Estate planning tools—wills, powers of attorney, healthcare directives, and beneficiary designations—help ensure that, if something happens, loved ones are protected and key decisions are made according to their wishes.
Finally, it is important to recognize that the sandwich years will not last forever. The most intense period of overlapping responsibilities usually spans a decade or two, after which certain burdens (such as tuition or active eldercare) may diminish. A well‑designed plan anticipates these phases and includes a strategy for increasing retirement contributions once major obligations are resolved. Knowing there is a roadmap can ease anxiety and help clients stay focused during demanding seasons of life. The challenges for those in the sandwich generation, usually ages 35 to 55, underscores why a coordinated, advisor‑led plan matters. By prioritizing retirement, planning realistically for education and eldercare, managing risk, and fostering clear family communication, you can support those you love today without sacrificing your own financial independence and dreams for tomorrow.