For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Tips for Women to Build Financial Independence

Tips for Women to Build Financial Independence

Traditionally, women have been the caretakers of both the older and younger generations of their families. But providing care for family members is becoming increasingly difficult, as doing so may require a leave of absence from work and drain one’s bank account.

Every woman needs to balance her financial past with her financial future.

Here are some tips to help you with the management of your personal finances so you can look towards the future and start building financial independence.

March 8, 2021
Tips for Women to Build Financial Independence
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

Traditionally, women have been the caretakers of both the older and younger generations of their families. But providing care for family members is becoming increasingly difficult, as doing so may require a leave of absence from work and drain one’s bank account.

Such income disruptions greatly affect a woman’s ability to save money, plan for retirement, and maintain financial security. In addition, older married women often provide care for their elderly husbands.

But who will help you when you require assistance? Even though younger family members may be more than willing to help, the costs of health care often exceed the amount of disposable income available to the average family. Perhaps, women and their family members need to look toward the future and start the planning process.

Your Planning Process

Every woman needs to balance her financial past with her financial future. By addressing the management of your personal finances as soon as possible, you can avoid disputes and build financial independence.

Here are a few things to think about as you start your financial planning process:

  • Durable Power of Attorney. This mechanism allows individuals to appoint a trusted relative or friend as a representative in legal and financial matters. The powers granted may be limited or broad in scope, and may vary from state to state. They remain in effect during disability or incompetence – although, in the event of incompetence, a guardian or conservator could revoke them. Some financial institutions are reluctant to recognize a durable power of attorney, so it is worthwhile to explore any potential problems beforehand.
  • Revocable and Irrevocable Trusts. A revocable trust allows you to retain control of your property, while delegating the responsibility for daily management to others. This arrangement gives you the flexibility to change the trust in any way, and at any time, as needs and circumstances dictate. As added protection, a revocable trust may remain unfunded as long as you are legally competent. On the other hand, when you reach a certain age and are willing to relinquish ownership of assets altogether, you may wish to consider establishing an irrevocable trust.
  • Informal Arrangements. You can also informally transfer property to your heirs, in many cases free of gift taxes, in exchange for being taken care of for the rest of your life. This arrangement, however, should be approached with extreme caution. Even with the best of intentions, it is possible that adult children could deplete assets through poor management, divorce, or creditor claims. Once the assets are gone, an aging parent could become dependent on the goodwill and financial circumstances of family members.

Review Your Plans Periodically

It may be necessary to periodically review these arrangements, as needs and circumstances change. You may also wish to consider consulting a qualified financial professional with experience in concerns facing today’s women.
Other content you may like

  • Year-End Charitable Giving Strategies

    December 11, 2024
    Charitable giving should be integrated into overall wealth management, with careful planning and an advanced strategy to make a more meaningful impact. There are also unique opportunities for high-net-worth individuals to maximize the impact of their contributions through these four popular strategies.
    Read this Article
  • Christmas Shopping Lessons for Investors

    December 7, 2021
    There’s a generational cycle that is both fascinating and important to understand as an investor. Find out why it’s important to ask yourself, “Is that investment an innovation or an improvement on an existing product?” It could explain why today’s business environment seems flush with billionaires younger than 30. It’s also helpful when you’re deciding to invest in the right new product – Facebook and not MySpace for instance.
    Read this Article
  • Could the Roth 401(k) Be Right for You?

    April 8, 2025
    What are the major differences between the traditional Roth IRA and the 401(k) Roth? There are benefits to the employer-offered 401(k) Roth, like the ability to save more than in a traditional IRA, however, since it is part of the 401(k), there are some restrictions.
    Read this Article
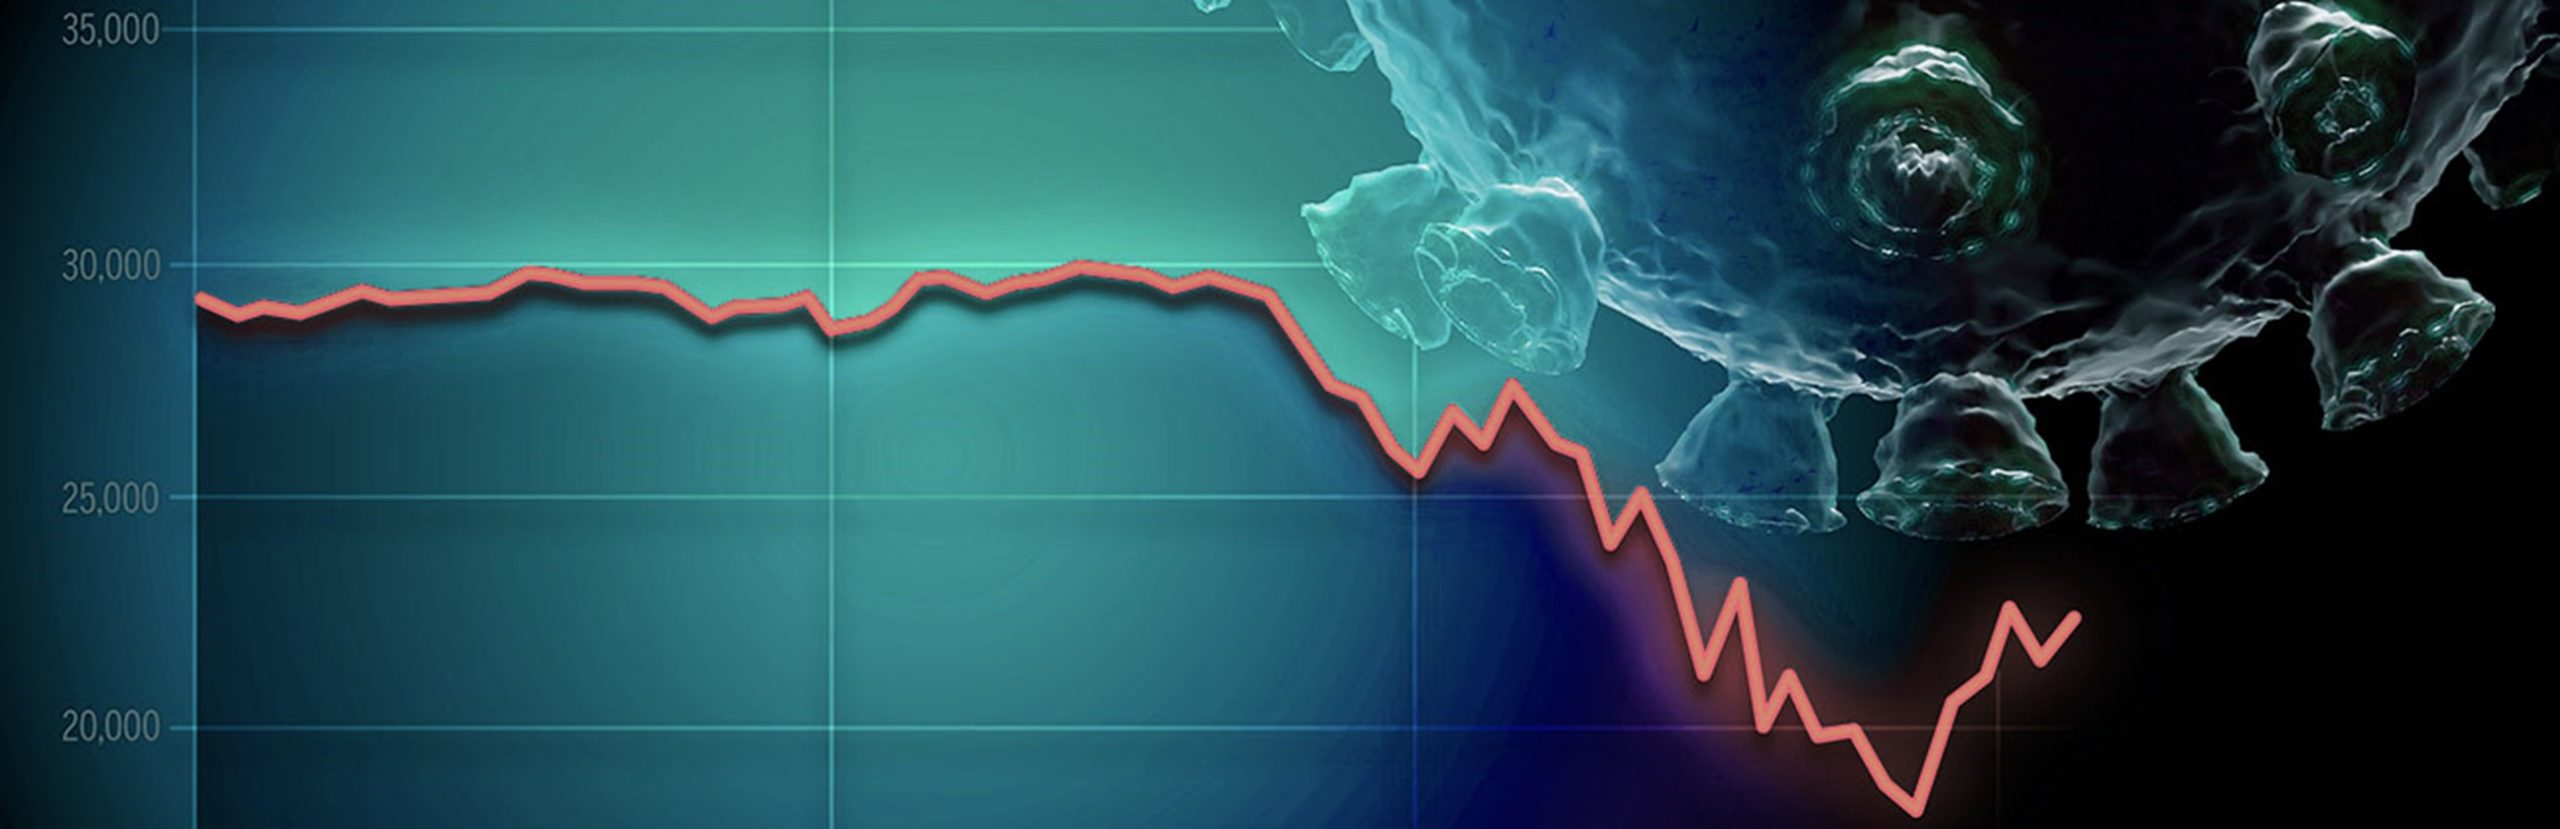
  • Wondering Whether You Missed the Recovery Image

    Wondering Whether You Missed the Recovery?

    October 19, 2020
    Why long-term investing success is about time in the market, not timing. Some investors are confident that they can time it perfectly and snap up equities when prices are low and shift into cash or bonds when the market hits its peak. This article brings up several reasons why investors run a big risk by selling when they believe stocks have reached their peak.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset