For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

7% Mortgages: Strategies for Buyers, Owners, and Empty-Nesters

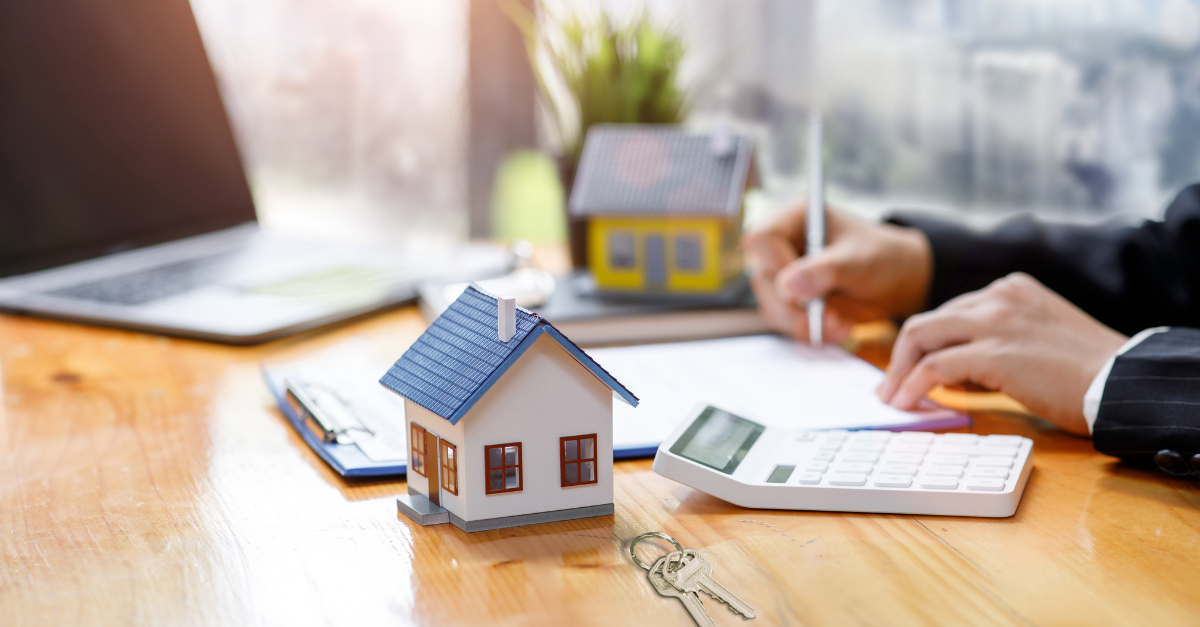
A business professional is sitting at a table or desk completing paperwork with a miniature home, calculator and set of keys in the foreground.

For anyone navigating the current housing market, understanding strategies to manage a 7% mortgage is crucial. This article explores different options for those desiring a housing change. Read on to find solutions and insights tailored to your unique situation.

August 12, 2025
A business professional is sitting at a table or desk completing paperwork with a miniature home, calculator and set of keys in the foreground.
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

High Rates Don't Have to Mean High Stress

With mortgage rates hovering around 7%, many people are reassessing their housing and financial decisions. After a decade of historically low borrowing costs, today’s environment presents new challenges. For prospective buyers, current homeowners, and empty-nesters alike, understanding how to navigate these changes is key. Fortunately, there are strategies to help move forward with clarity and confidence.


For Buyers: Marry the House, Date the Rate

For those looking to purchase a home, a 7% interest rate can feel discouraging. However, it’s important to remember that the mortgage rate selected today doesn’t have to be permanent.

Strategies to consider:

  • Negotiate with Sellers: Slower buyer activity in today’s market creates room for price reductions, seller credits, or a temporary interest rate buydown.
  • Consider an ARM (Adjustable-Rate Mortgage): Buyers not planning to stay in a home long-term might benefit from lower initial payments offered by ARMs.
  • Refinance Later: Many are approaching their mortgage decision as a temporary step, with the intent to refinance if rates decline in the future.

The key is purchasing a home that fits within they buyer’s current budget and long-term financial stability, regardless of the prevailing interest rate.


For Current Homeowners: The Golden Handcuff Effect

Homeowners who secured a 2–4% mortgage find themselves in an enviable position—one often described as wearing “golden handcuffs.” These low monthly payments are a significant asset, yet they may limit flexibility.

Strategic moves to evaluate:

  • Home Equity Utilization: Instead of selling and forfeiting a favorable rate, homeowners might consider a home equity line of credit (HELOC) to fund projects, education, or investments.
  • Renting Out Instead of Selling: For those needing to relocate, converting a home into a rental can generate income while preserving a valued mortgage.
  • Revisit the Broader Financial Plan: A low mortgage rate should not overshadow larger retirement or lifestyle priorities. A Strong Valley advisor can help weigh available options in the context of overall goals.

For Empty-Nesters: Freedom May Be Worth More Than a Low Rate

Many retirees or near-retirees are living in homes that have appreciated significantly—and carry very low mortgage rates. Yet remaining in place purely for financial reasons may delay important lifestyle transitions.

Options to consider:
  • Downsize Strategically: While a new mortgage may come with a higher rate, some downsizers may be able to buy a new home outright, or take on a modest loan. In many cases, the financial trade-off is well worth the lifestyle improvement.
  • Prioritize Lifestyle Goals: Questions such as proximity to family, lower maintenance responsibilities, and freedom to travel often outweigh the benefit of a low mortgage payment.
  • Tax & Estate Planning: Selling a home can unlock opportunities in charitable giving, tax planning, or simplifying estate considerations—all of which can have long-lasting impact.

Key Takeaways:

  • A 7% mortgage rate should not paralyze decision-making—strategic options exist at every stage of life.
  • Buyers may benefit from negotiating terms now or planning to refinance later.
  • Homeowners can explore home equity strategies to avoid giving up favorable rates.
  • Empty-nesters should weigh the benefits of mobility and planning opportunities against the comfort of staying put.

Other content you may like

  • Inflation Steadily on the Decline

    Inflation Steadily on the Decline

    May 1, 2023
    In this recap of March, Strong Valley team members Chris Conner, Kyle Trippel and Jason Rankin discuss the larger context of the recent bank failures; how dramatic rate increases played a part and how the market reacted. Could interest rate cuts be on the horizon? They also delve into the newly enacted Secure Act 2.0, touching some of the high points affecting retirement vehicles.
    Read this Article
  • Sticky Inflation

    Making Sense of Sticky Inflation Effects

    October 1, 2023
    Strong Valley team members Adam and Chris give a recap of September along with a discussion about how interest rates are being affected by Sticky Inflation. They also touch on the housing market, college values, and an update on the Secure Act 2.0 details that could affect your RMD.
    Read this Article
  • A couple sitting at a table and filling out a document or form.

    The Value of Bonds

    April 24, 2026
    Bonds can be an important component in a balanced investment portfolio, offering a reliable income stream. They can also help balance risk in uncertain times. Understanding bond dynamics, value and intricacies, can significantly enhance your investment strategy.
    Read this Article
  • Stocks Lose Money for the 26th Time

    Don't Judge Diversification on Feelings

    January 29, 2023
    Focusing on what happened in 2022, this Student of the Market shows an overview of last year’s performance compared to similar years in the market’s history. This may be a window into the possibilities for 2023 and the future of Federal Reserve rate hikes. Also a look at the numbers showing that even though portfolio diversification works, it doesn’t always feel good.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset