For clients of Kate Eiland, please CLICK HERE to see important details related to the Strong Valley transition.
Article

Valuing Liabilities like Assets

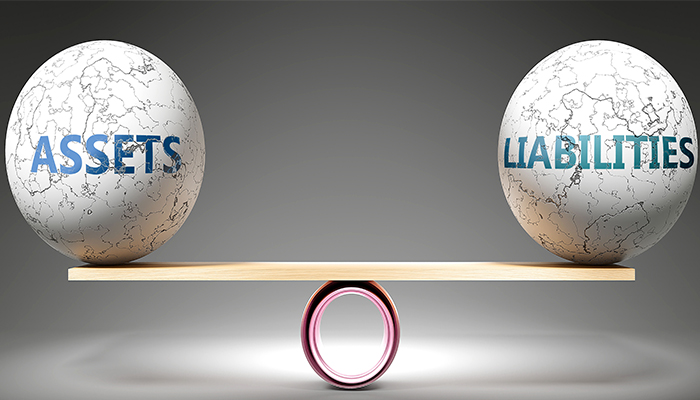
It’s natural for you to gravitate towards the idea of financial planning being focused on growing assets such as stocks, bonds and real estate. Many are surprised to learn that developing a comprehensive financial strategy doesn’t only involve focusing on what you own, but also what you owe.

September 10, 2024
Important Disclosure: Content on our website and in our newsletters is for informational purposes only. The information provided may (or may not) directly apply to your situation. We recommend that readers work directly with a professional advisor when making decisions in the context of their specific situation.

When the topic of financial planning comes up, most individuals naturally gravitate towards the idea of growing their assets. Stocks, bonds, real estate, and retirement accounts usually dominate these discussions. However, a comprehensive financial strategy doesn't only involve focusing on what you own, but also on what you owe. Liabilities, or the debts one owes, are just as crucial to understand and manage, especially in an economic environment of rising interest rates.

Why Liabilities Matter

  1. Net Worth Calculation: At its core, a person's net worth is calculated as assets minus liabilities. If we only focus on half the equation, we can get a distorted picture of financial health. A person might own assets worth a million dollars but could be deep in debt, resulting in a low or even negative net worth.
  2. Cash Flow Implications: Monthly debt payments can take up a significant portion of an individual's income.

    This can restrict the ability to invest for the future, save, or even cover daily living expenses. Understanding and managing liabilities helps ensure a smoother cash flow.
  3. Interest Rate Risk: With floating rate debt, the interest rate isn't fixed but varies based on market conditions. In a scenario of rising interest rates, the cost of servicing this debt can shoot up rapidly, making it more expensive for the borrower.

Treating Liabilities Like Assets

Given the importance of liabilities, here's how one can give them the same attention as assets:

  1. Regular Review: Just as one would review an investment portfolio periodically, it's essential to review outstanding debts. This includes checking for interest rates, payment terms, and the remaining balance.
  2. Refinancing Opportunities: As markets evolve, there might be chances to refinance debts at a lower interest rate or better terms. This can result in significant savings over time.
  3. Prioritizing Repayment: Not all debts are created equal. Some might have a higher interest rate, while others might be tax-deductible. By understanding the nature and cost of each liability, one can create a repayment strategy that maximizes financial benefits.
  4. Establishing an Emergency Fund: One of the best ways to prevent unnecessary debt is by having an emergency fund. This cash reserve can cover unexpected expenses, reducing the need to rely on high-interest credit options.
  5. Considering Debt in Investment Strategy: If an investment opportunity offers a return of 6%, but one has outstanding debt with an interest rate of 8%, it might make more financial sense to pay off the debt first rather than invest. It's essential to weigh the prospective returns against the guaranteed cost of the debt.

A holistic financial plan is a two-sided coin: assets on one side and liabilities on the other. By valuing liabilities in the same way we value assets, we not only get a clearer picture of our financial health but also make informed decisions that set the stage for long-term financial stability and growth. As interest rates evolve and economic conditions shift, understanding and actively managing liabilities becomes not just a good practice, but a necessity.
Other content you may like

  • Largest Inflation Increase Since December 1981

    Largest Inflation Increase Since December 1981

    June 14, 2022
    Your long-term retirement strategies must account for inflation, which decreases the purchasing power of your money in the future. With inflation appearing to go up every single month in 2021 and 2022, it’s important to consider the historical averages and record highs to create a good plan. There are ways that you can prepare for a decrease in the purchasing power of your dollar over time.
    Read this Article
  • Mid-Quarter Roundtable Highlights

    Podcast Highlight - Is It Safe? Money Market and Bank Deposit Sweeps

    December 8, 2022
    There is no riskless asset. Even if you had it all in green – someone could steal it, your house could catch fire, or inflation could devalue it. The team points out some of the pros and cons of money market vs. bank deposit.
    Read this Article
  • A couple sitting at a table looking at a laptop

    Strategies for Lowering Retirement Income Taxes

    October 10, 2025
    Have you considered how to minimize income taxes in retirement? This article covers strategies that can potentially reduce the tax burden on your retirement income. It provides insight into some beneficial approaches you can consider in your long-term approach.
    Read this Article
  • How to Help Aging Parents

    How to Help Aging Parents

    November 30, 2021
    Preparing for the potential decline of financial capacity to manage your finances in your own best interest, is as important as planning for long-term-care expenses or keeping your estate plan up to date. This article gives practical steps to prepare and plan ahead.
    Read this Article
  • The link you have selected is located on another server. The linked site contains information that has been created, published, maintained, or otherwise posted by institutions or organizations independent of this organization. We do not endorse, approve, certify, or control any linked websites, their sponsors, or any of their policies, activities, products, or services. We do not assume responsibility for the accuracy, completeness, or timeliness of the information contained therein. Visitors to any linked websites should not use or rely on the information contained therein until they have consulted with an independent financial professional. Please click “Continue to Link” to leave this website and proceed to the selected site.
    phone-handset